What is P.P.36?
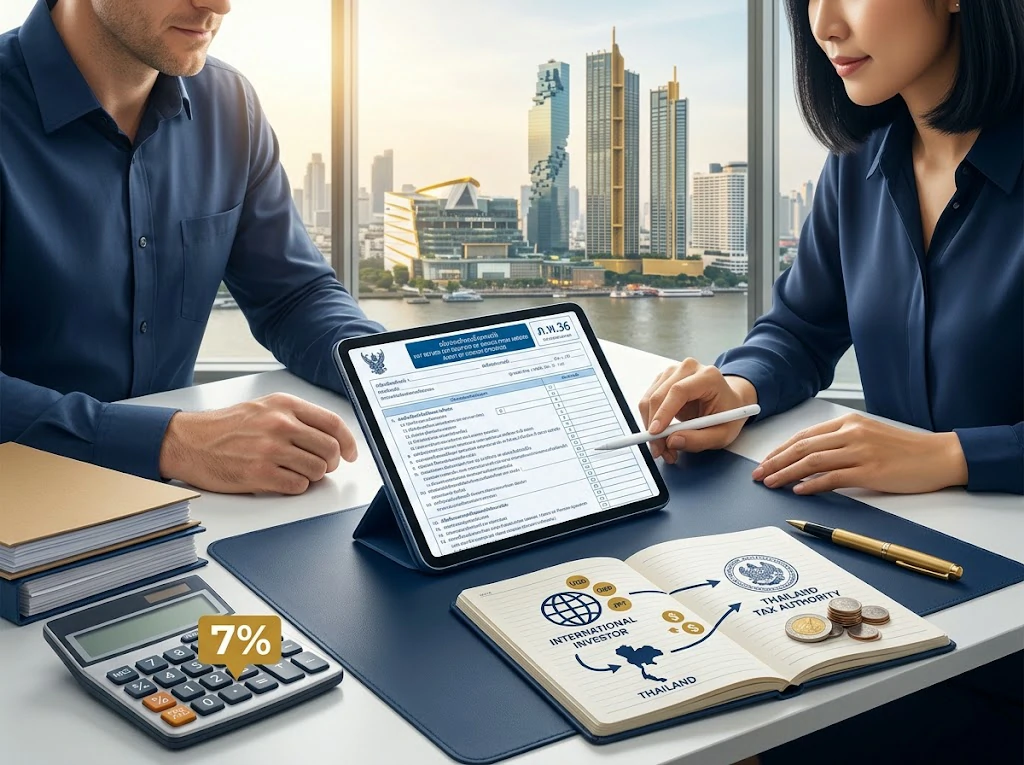
P.P.36 is a Value Added Tax (VAT) return used to remit VAT in cases where the payer is responsible for paying VAT on behalf of a foreign seller or service provider that does not carry on business in Thailand.
The current VAT rate is 7%.
Who is required to file P.P.36?
- A business that is registered for VAT in Thailand and makes payments for services to a foreign company that does not have a branch or business presence in Thailand.
- Businesses that are not VAT-registered are generally not required to file P.P.36. Businesses that are VAT-registered are required to file P.P.36 when the relevant conditions under Thai VAT law are met.
Do Online Businesses Need to File P.P.36?
Whether a business sells products online through platforms such as Shopee, Lazada, TikTok, Facebook, Instagram, YouTube, or LINE, the applicable rules should be considered under Thailand’s e-Service VAT provisions, which have applied since 1 September 2021.
If a Thai business pays for services to an overseas service provider and the service is utilized in Thailand, the Thai business may be required to file P.P.36 and remit the applicable VAT.
The VAT paid under P.P.36 may generally be claimed as input VAT, subject to the relevant requirements under Thai tax law.
VAT Rate and Calculation
- VAT rate: 7%
- VAT is generally calculated based on the amount paid for the service to the overseas service provider, subject to the applicable tax rules.
Example:
If a company pays THB 10,000 for a service provided by an overseas service provider:
THB 10,000 × 7% = THB 700 Therefore, THB 700 is the VAT amount to be remitted
Filing Deadline
P.P.36 must generally be filed online by the 15th day of the following month.